
Missed Your Form 5472? What Foreign LLC Owners Should Do Next
Missed Form 5472 for your US LLC? Here's how to find the missing years, file them late, explain the delay, and why acting before the IRS contacts you matters.
By IncorpLab™ Team · Last checked against the IRS Instructions for Form 5472 (Rev. December 2024) and the IRS Delinquent International Information Return Submission Procedures on October 16, 2026
Short answer: If your foreign-owned LLC missed Form 5472, file every missing year as soon as you can, ideally before the IRS contacts you. Each year needs a complete Form 5472 with a pro forma Form 1120, and you can attach a statement explaining why it was late. Filing late doesn't ensure penalty relief, but leaving returns unfiled is worse.
Key takeaways
- Start by listing every tax year since formation and checking which returns were actually filed.
- Each missing year needs its own complete Form 5472 with a pro forma Form 1120.
- The IRS's delinquent-filing procedure is only available if you haven't been contacted about the missing returns and aren't under examination.
- Penalties can still be assessed at first, even with a reasonable-cause statement attached.
- Keep proof of every filing.
In this guide: Find the missing years · Catch-up steps · Before or after a notice · Reasonable cause · Penalties · FAQ
Which years might you have missed?
Every tax year since your LLC was formed, unless you can prove a return was filed. Foreign-owned single-member LLCs must file Form 5472 for each year with a reportable transaction, which in practice means almost every year. An LLC formed in 2023 would normally owe returns for 2023, 2024 and 2025 by now.
For each year, check whether you have a fax confirmation, mail receipt or copy of the filed return. If you don't, and you don't know whether a provider filed it, treat it as missing. If you're not sure what Form 5472 covers, start with our guide to Form 5472 for foreign-owned US LLCs.
How do you catch up on missed Form 5472 filings?
Find the missing years, prepare a complete return for each one, then file them with an explanation and keep proof. Each year is a separate filing with its own Form 5472 and pro forma Form 1120.
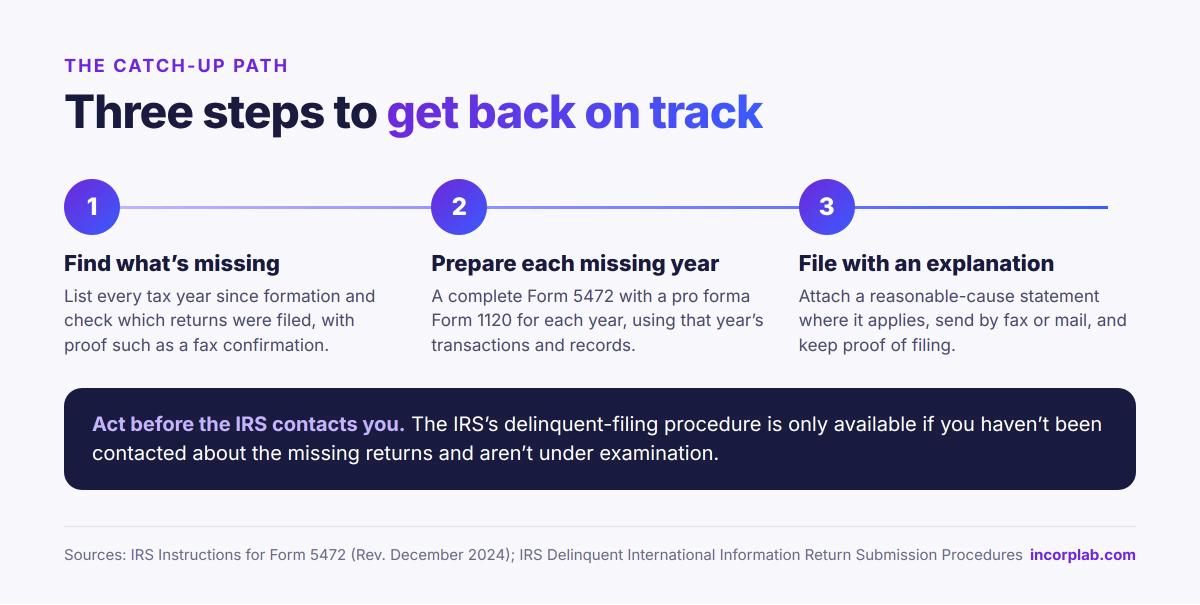
- Find what's missing. List each tax year since formation and mark which returns you can prove were filed.
- Prepare each missing year. Use that year's transactions between you and the LLC: money you put in, money you took out, loans and payments. Bank statements and receipts are your main records.
- File with an explanation. Send each return by fax or mail, attach a reasonable-cause statement where it applies, and keep the fax confirmation or mail receipt.
Does it matter if the IRS has already contacted you?
Yes. The IRS's Delinquent International Information Return Submission Procedures are only available if you haven't been contacted about the missing returns and aren't under civil examination or criminal investigation. Once you've received a notice, respond to it by its deadline instead.
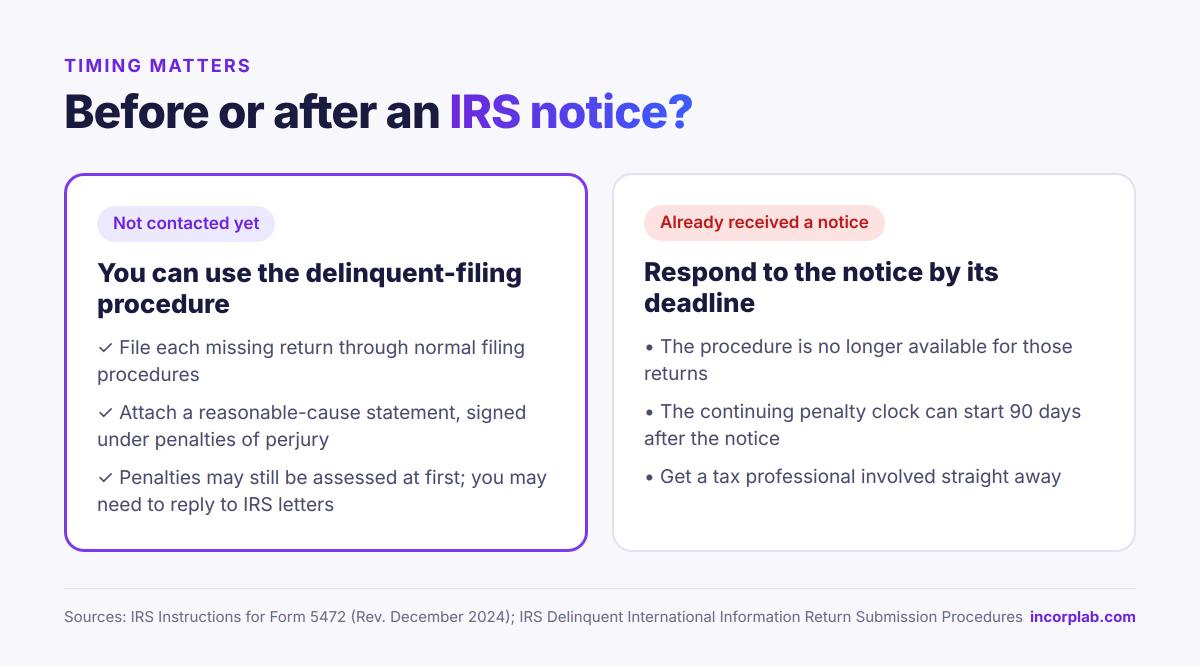
That's the main reason to act early. Filing before the IRS finds the gap gives you a recognised route and the chance to explain the delay up front.
What is a reasonable-cause statement?
A written explanation of why a return was filed late, showing that you acted with ordinary care. It is attached to each delinquent return and signed under penalties of perjury. Being unaware of the rule may not be enough on its own, so the facts and how they're presented matter.
The IRS warns that penalties may be assessed during processing without considering the attached statement, and that you may need to reply to correspondence and resubmit the explanation. Relief is never automatic, which is why many owners have a tax professional prepare the statement.
What penalties could apply?
The penalty for each Form 5472 filed late, not filed, or substantially incomplete can be $25,000. If the failure continues more than 90 days after an IRS notice, an extra $25,000 can be added for each further 30 days. The IRS decides whether to charge, reduce or remove a penalty based on the facts, including any reasonable cause you show.
Frequently asked questions
Can I just start filing from this year and skip the past years?
Not safely. Each missed year remains unfiled, and penalties are assessed per return. Filing the current year draws attention to the gap without fixing it.
Will the IRS automatically waive penalties if I file late voluntarily?
No. A reasonable-cause statement can support relief, but the IRS may assess penalties first, and you may need to respond to its letters.
What if a formation provider was supposed to file and didn't?
Get whatever records they have, confirm which years are missing, and file those years. Reliance on a provider may be part of your explanation, but it's assessed case by case.
I don't have bank statements for an old year. What can I use?
Receipts for fees you paid, payment confirmations, and records from your personal account showing money sent to or received from the LLC. Your tax professional can advise on what's enough.
Does my LLC owe US tax because I missed Form 5472?
Not because of the missed form. Form 5472 is an information return. Whether tax is owed depends on other factors, such as whether the LLC has US business income.
How IncorpLab can help
Not sure which years are missing? Use our free Form 5472 compliance check. Send your LLC name and formation date, and we'll tell you which years must be filed and what it costs to file them. Missing years are prepared and filed by our partner tax professional, who can also prepare the reasonable-cause statement.
This article is general information, not tax or legal advice. Every late-filing situation is different, so speak to a tax professional before filing. IncorpLab is a private document preparation and filing service and is not affiliated with the IRS.
Sources
- IRS: Delinquent International Information Return Submission Procedures
- IRS: Instructions for Form 5472 (Rev. December 2024)
Want to use these infographics on your own site or in a post? You're welcome to, with a link back to this guide.